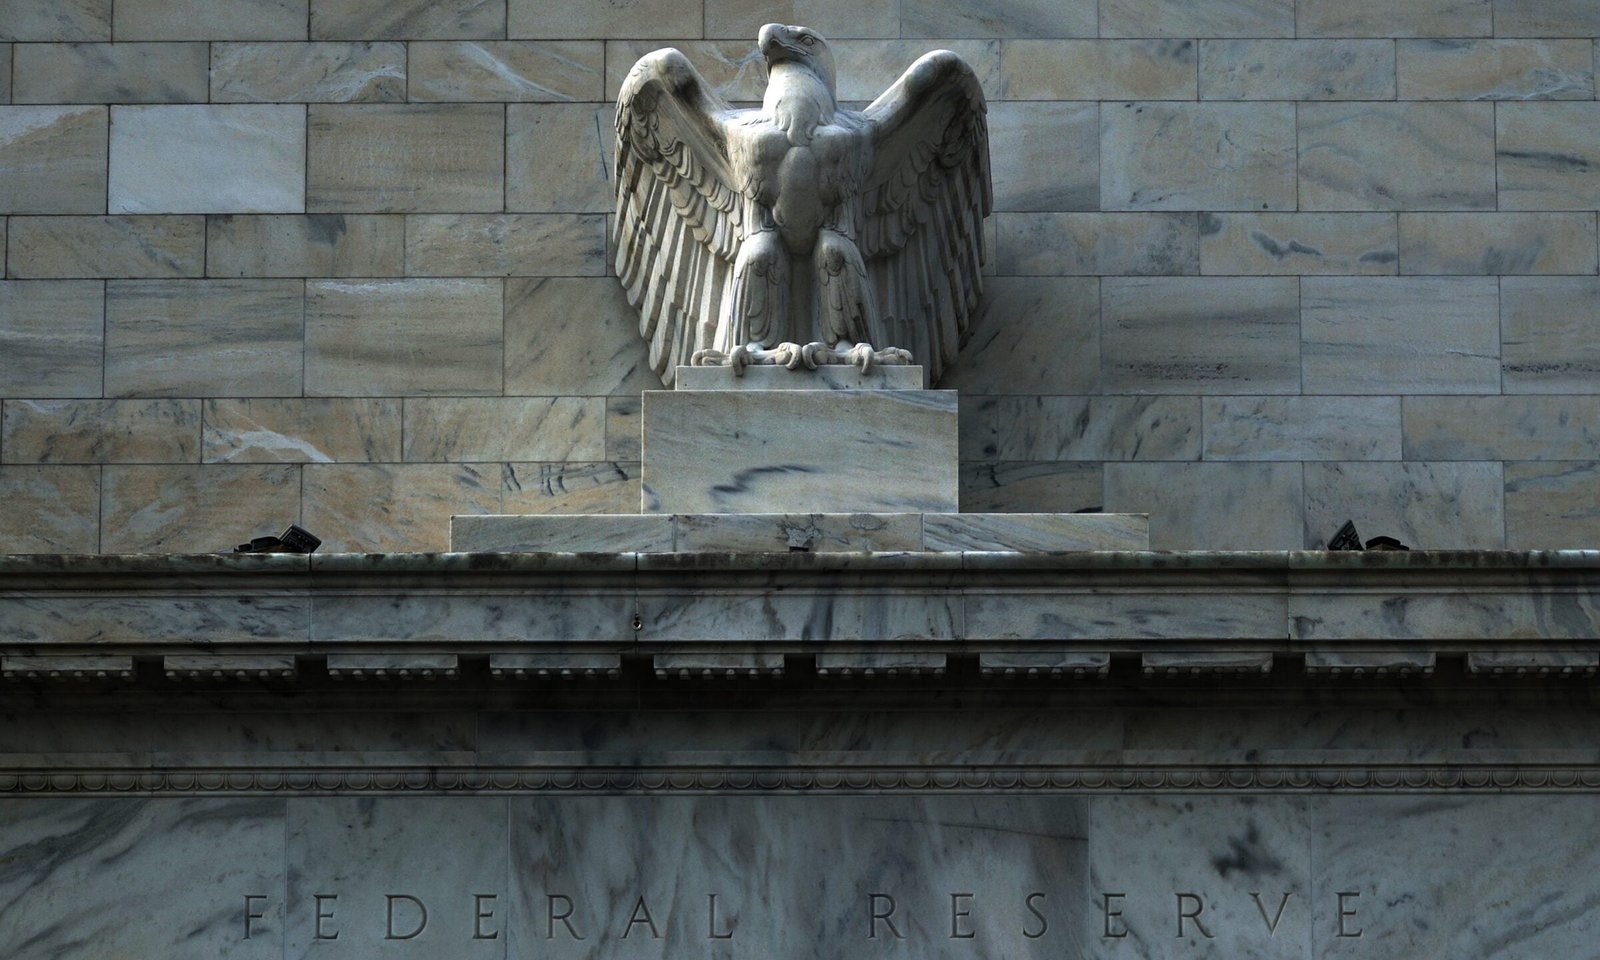
The Federal Reserve has increased its benchmark interest rate by a quarter percentage point, bringing the federal funds target range to 3.75%-4% and making it more expensive for consumers to take on debt. This is the first rate hike under newly appointed Fed Chair Kevin Warsh and the first since 2023, with inflation remaining above the Fed’s 2% target. The decision was unanimous.
As gas prices continue to rise above $4 per gallon on average and tensions escalate in Iran, the Fed’s move aims to prevent broader economic impacts. Warsh emphasized that while the Fed cannot control individual prices, they will work to prevent second and third-order effects on the economy.
For consumers, higher rates mean borrowing becomes costlier while savings may become more rewarding. Financial products like credit cards, auto loans, and personal loans may see increased interest rates. Mortgage rates could also rise, making home buying less affordable for some. However, savers may benefit from higher yields on savings accounts and CDs.
The Fed’s focus on achieving stable prices is intended to help those who rely on their paychecks to make ends meet. Warsh highlighted the importance of stable prices in ensuring real take-home pay increases for workers.
Looking ahead, data reports will guide the Federal Open Markets Committee’s future actions. The majority of FOMC members anticipate at least one more 25-basis-point increase this year. Futures markets suggest a possibility of another hike at the Fed’s October and December meetings.
For a more detailed understanding of how the rate hike will impact specific financial products, further analysis is recommended. The sentence is not provided. Please provide the sentence you would like me to rewrite.