Authored by Karl-Friedrich Israel via The Daily Economy,
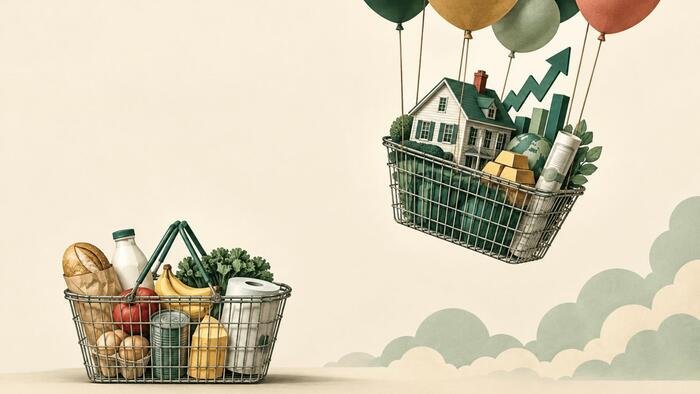
The current situation in America highlights a significant disparity between the median home price of $440,600 and the median household income of approximately $84,000 annually. This growing gap has resulted in a larger portion of Americans being priced out of the housing market, while existing homeowners and stockholders have seen their wealth increase. The wealth disparity between renters and homeowners is currently at its highest level on record. Meanwhile, the equity markets continue to reach new highs. Surprisingly, none of these factors are officially considered as part of inflation.
In a previous article, it was explained how the Consumer Price Index (CPI) fails to account for a significant portion of household expenses due to government spending financed by taxes. This is one blind spot of the CPI. Another, more impactful blind spot is the exclusion of asset prices such as stocks and homes from conventional inflation measures.
Exclusion of Asset Prices from CPI
The exclusion of asset prices from the CPI can be traced back to the index-number theory developed by Gottfried Haberler in 1927. According to this theory, the standard price indices used by economists are only accurate measures of an individual’s cost of living under specific assumptions, one of which is that the individual is a pure consumer without savings, investments, or real estate properties bought for reasons other than personal use. This assumption is necessary for the CPI to accurately reflect the cost of living for such individuals, hence the exclusion of asset prices.
While the CPI does include housing costs through “owners’ equivalent rent,” it does not consider the actual price of homes as assets or the value of equities in the index. This is because a pure consumer, as defined by the CPI, does not hold any assets. Therefore, the CPI is unable to capture the inflationary pressures on asset prices, leading to a significant gap between the appreciation of assets and consumer price inflation.
Impact of Excluding Asset Prices
The exclusion of asset prices from the CPI has resulted in a distorted view of inflation in the economy. Over the past three decades, while the CPI has shown modest growth, asset prices such as stocks and homes have experienced exponential increases. For instance, the S&P 500 has outpaced consumer prices by more than threefold, and home prices have grown at a rate double that of the CPI. This discrepancy has widened the wealth gap between asset owners and those struggling to enter the market.

This discrepancy can be partially attributed to the monetary policy since the mid-1990s, leading to a divergence between money supply growth and real economic growth combined with consumer price inflation. The excess liquidity created by the government has not been reflected in consumer prices but has instead fueled the inflation of asset prices.
Conclusion
The exclusion of asset prices from conventional inflation measures has created significant blind spots in understanding the true economic landscape. The CPI’s failure to account for government-financed consumption and asset price inflation has resulted in a distorted view of inflation and wealth distribution in the economy. It is essential to recognize these blind spots and consider alternative measures to provide a more comprehensive understanding of economic realities.