Close Menu
  • Home
  • Economic News
  • Stock Market
  • Real Estate
  • Crypto
  • Investment
  • Personal Finance
  • Retirement
  • Banking

Subscribe to Updates

Get the latest creative news from FooBar about art, design and business.

What's Hot

SwissBorg’s USDC integration bypasses PlaygroundBridge’s up to 25% fees on Arc Network

September 20, 2026

Mortgage Rates Today, Friday, September 18: No Change

September 20, 2026

The Apocalyptic Game: Panic And Opportunity

September 20, 2026
Facebook X (Twitter) Instagram
  • Contact Us
  • Privacy Policy
  • Terms Of Service
Sunday, September 20
Doorpickers
Facebook X (Twitter) Instagram
  • Home
  • Economic News
  • Stock Market
  • Real Estate
  • Crypto
  • Investment
  • Personal Finance
  • Retirement
  • Banking
Doorpickers
Home»Personal Finance»Mortgage Rates Today, Friday, September 18: No Change
Personal Finance

Mortgage Rates Today, Friday, September 18: No Change

September 20, 2026No Comments5 Mins Read
Facebook Twitter Pinterest LinkedIn Tumblr Email
Share
Facebook Twitter LinkedIn Pinterest Email

It’s been a long week, and even mortgage rates are taking a beat today, holding steady with yesterday’s levels.

The average interest rate on a 30-year, fixed-rate mortgage remained at 7.05% APR, according to rates provided to BW by Zillow. This is unchanged from yesterday and four basis points lower than a week ago. (See our chart below for more specifics.) A basis point is one one-hundredth of a percentage point.

Nah, mortgage rates aren’t just tired. Here’s what’s actually going on, and it’s what I said could happen in an article that came out on Wednesday (specifically, in the section headed “Today’s rate hike could provide a little relief”).

Mortgage rates are pegged to the yield on the 10-year Treasury, and longer-term bond yields are falling back a little. The bond market’s been unhappy with the Federal Reserve’s inaction on inflation, so the Fed hiking the funds rate to fight inflation is welcome news. When bond yields are more chill, mortgage rates are, too.

For more on the ramifications of Wednesday’s Fed meeting and what it could mean for mortgage rates, keep reading below the chart.

P.S.: While the economy never sleeps, markets are closed on the weekends. The rates you see Friday are unlikely to change much (if at all) until Monday.

Average mortgage rates, last 30 days

🤓 Kate on Rates: September 17, 2026
Video thumbnail

📈 What influences mortgage rates?

Mortgage rates are constantly changing, since a major part of how rates are set depends on reactions to new inflation reports, job numbers, Fed meetings, global news … you name it. For example, even tiny changes in the bond market can shift mortgage pricing.

The Federal Reserve raising the target for the federal funds rate 25 basis points wasn’t the biggest news to come out of this week’s Fed meeting. By the time the meeting was imminent, market odds were over 92% in favor of a hike. Mortgage rates had already moved sharply upward on last week’s inflation data, numbers which also convinced markets that the Fed would have to hike.

A little bit of a side note, but for someone who has such conviction that the Fed’s decisions shouldn’t hang on any particular bits of data, chair Kevin Warsh’s opening remarks at the post-announcement press conference sure made it sound like that data was important.
“This summer’s inflation readings do not tell me that underlying trends have meaningfully improved,” Warsh said. “Based on the most recent CPI and PPI data, the 12-month change in total PCE prices likely was around 3.6% in August. Core PCE and CPI prices are running at about 3.2, and 2.4% respectively.”

Regina George Mean Girls so you agree meme in reference to the September Fed meeting

BTW, August PCE comes out Sept. 30.

But anyway.

The bigger news out of the September meeting wasn’t the rate hike that basically everyone expected, it was the potential for additional rate hikes on the way. The Fed released an updated Summary of Economic Projections, where the committee members all shared their anonymized predictions for major metrics. (Except for Warsh, who refuses to participate.)

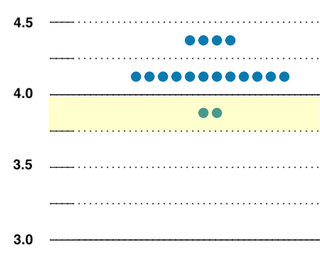
One of the most closely watched is the “dot plot,” where each dot represents an estimate of the appropriate level for the federal funds rate — the overnight borrowing rate that the Fed adjusts — at the end of each year. Looking at the previous round of projections for 2026 versus the ones released Wednesday shows a pretty stark difference, and not just because they had to cram most of the dots into one row in September.

Federal Reserve Dot Plot: June vs. September

Each dot represents an individual estimate for where the federal funds rate should be at the end of 2026.

June predictions
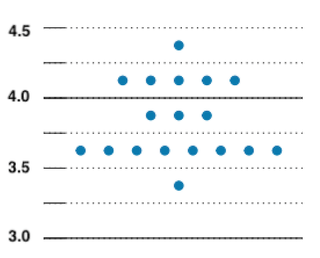
June predictions for the funds rate from the Federal Reserve

September predictions

September funds rate target predictions from the Federal Reserve

The yellow shading indicates the current level.

Source: Federal Reserve Summary of Economic Projections

The majority of meeting participants think that, by the end of 2026, the target for the funds rate should be 25 basis points higher than it is now — one more little hike. But there’s also a decent contingent who think it should go 50 basis points higher, which could be spread out between the October and December meetings, or be one sizable hike, probably in December. (Even though the Federal Reserve is politically independent, there’s a lot of chatter that a rate hike right before the midterm elections could be perceived as a political move.)

Parsing Warsh’s words at the press conference also has folks thinking this isn’t a one-and-done rate hike. (I should also note that this is pretty much exactly what Warsh doesn’t want markets doing.

Warsh mentioned removing a “dose of accommodation” from the financial conditions, indicating a stronger economy. With the possibility of additional rate hikes, markets are anticipating a higher rate environment. While this may relieve some bond market stress, mortgage rates are unlikely to drop. Refinancing could be a good option if your current rate is significantly higher than today’s rates. Consider your goals and use tools like BW’s refinance calculator to estimate savings. There is no perfect time to start shopping for a home, as long as you can afford the mortgage at current rates. Focus on getting preapproved and understanding your budget. Locking in your rate can provide peace of mind, especially if your lender offers a float-down option to take advantage of lower rates. Rates can fluctuate frequently, so staying informed is key. If you are satisfied with the agreement you currently have, it is acceptable to finalize your commitment. Can you please rewrite the sentence for me?

Change Friday Mortgage Rates September today
Share. Facebook Twitter Pinterest LinkedIn Tumblr Email

Related Posts

Quiz: What’s the Best Way to Make Money?

September 19, 2026

Locked Out: Should You Take ‘Free Money’ to Buy a Home?

September 19, 2026

How I Earned 1 Million Points With My Family Cruise Booking

September 18, 2026
Add A Comment
Leave A Reply Cancel Reply

Top Posts

Iran Says US-Israeli Attack Hit Elementary School, Killing 85+ Girls

February 28, 20265 Views

5 popular annuities for retirees

October 3, 20245 Views

Mortgage Rates Today, Monday, September 15: Heading Lower

September 15, 20259 Views
Stay In Touch
  • Facebook
  • YouTube
  • TikTok
  • WhatsApp
  • Twitter
  • Instagram
Latest
Crypto

SwissBorg’s USDC integration bypasses PlaygroundBridge’s up to 25% fees on Arc Network

September 20, 20260
Personal Finance

Mortgage Rates Today, Friday, September 18: No Change

September 20, 20260
Economic News

The Apocalyptic Game: Panic And Opportunity

September 20, 20260
Facebook X (Twitter) Instagram Pinterest
  • Contact Us
  • Privacy Policy
  • Terms Of Service
© 2026 doorpickers.com - All rights reserved

Type above and press Enter to search. Press Esc to cancel.